

Stocks discussed in the “STOCK STORY” series are NOT RECOMMENDATIONS to buy or SELL. They are a documentation of our study of the company’s business. Please consult your financial advisor and do your own due diligence before investing.
If you like watching more than reading, the YouTube video is here.
An orange growing on an apple tree will be misunderstood.
Bite into it like an apple, and you will be disappointed.
Peel away the layers, however, and you may start to see it differently.
The story of Rossell Techsys is, in many ways, similar to this metaphor.
We explore how a business that began as a small division inside a tea company has grown into a business larger than its parent.
Like what you’re reading?
Get the actual portfolios and buy/sell recommendations behind it → intelsense.in
Also available as ready-to-invest smallcases: intelsense.smallcase.com
For investing in our PMS, reach out to us at equity@shreerama.co.in
I. The Orange on the Apple Tree
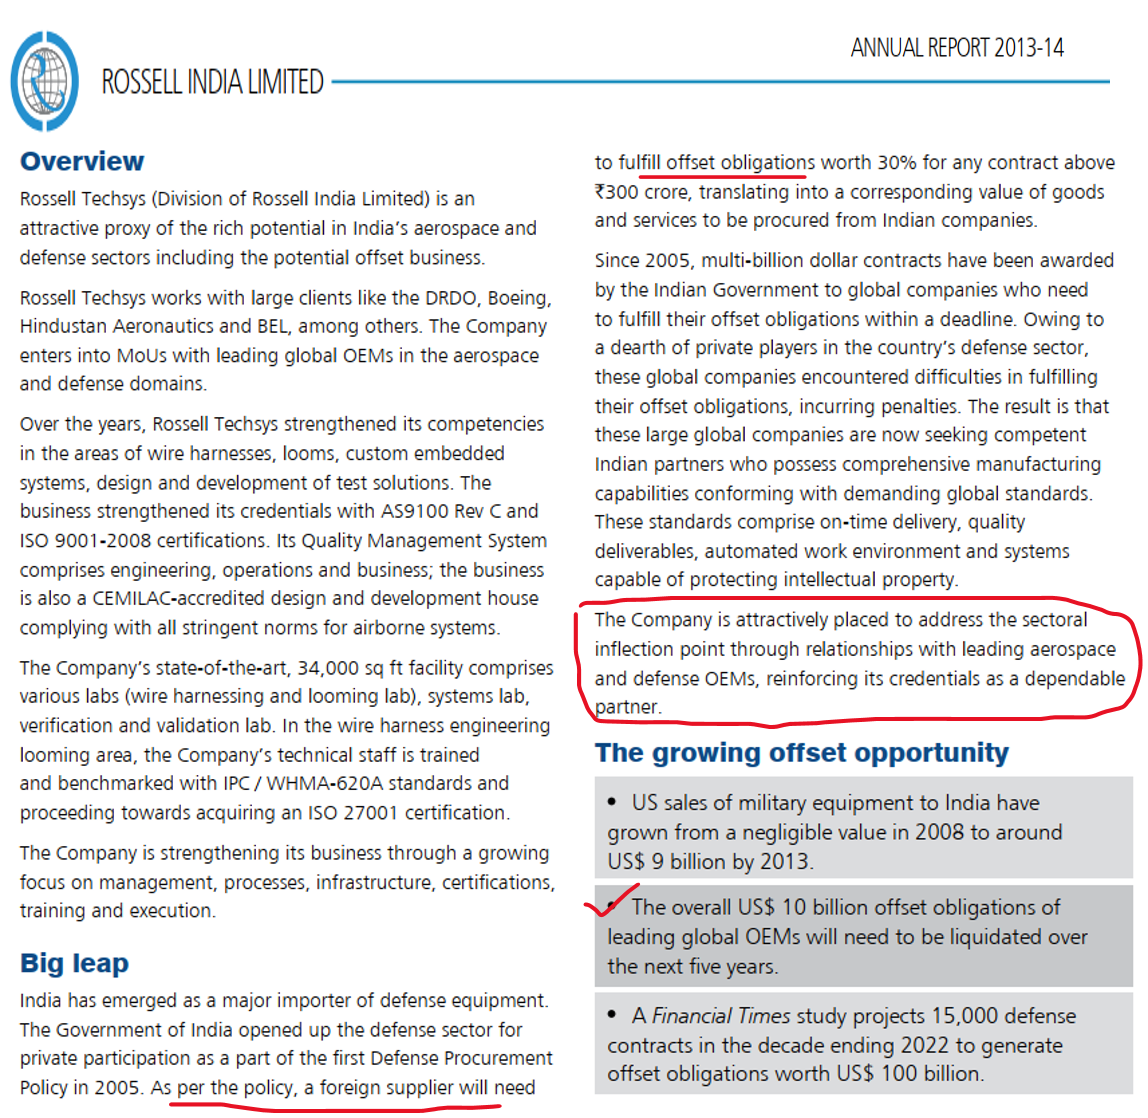
Around 2010–11, India’s defence procurement ecosystem was creating a new opportunity. Large contracts awarded to foreign OEMs came with offset obligations — requiring a portion of the value to be sourced from Indian companies.
Global aerospace companies therefore needed Indian suppliers that could meet the exacting requirements of the industry.
Rossell India Limited — which owned seven tea estates in Assam and was engaged in the cultivation, manufacture and sale of bulk tea — saw an entry.
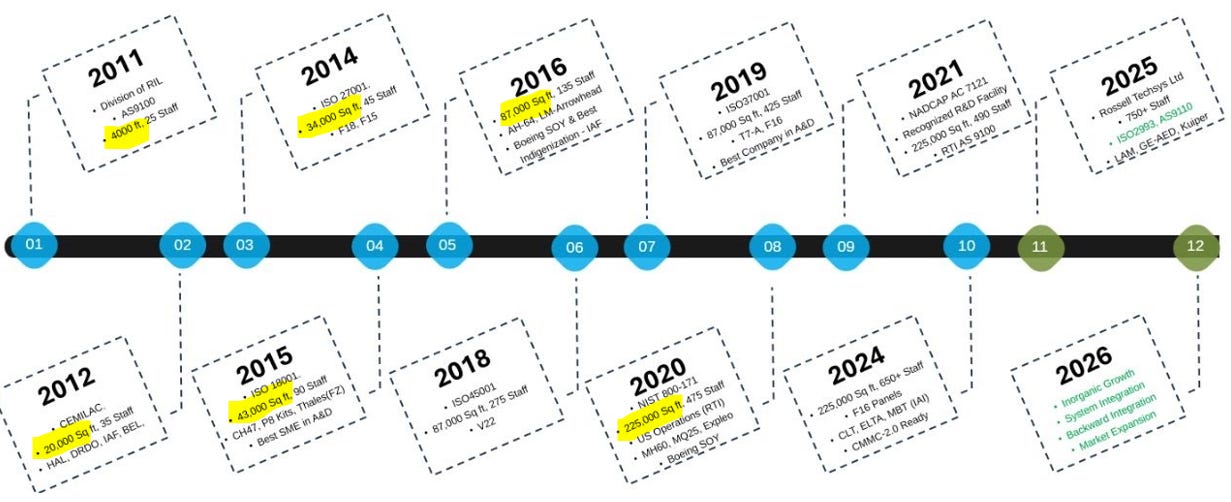
It established an Aerospace & Defence division in 2011 under the brand name Rossell Techsys and began operations with just 4,000 sq ft and 25 employees.
The initial focus was on relatively specialised pieces of the aerospace value chain — EWIS and wire harnesses, automated test equipment, test jigs and embedded software.
Then came the first major breakthrough.
In FY13-14, Rossell Techsys received its first export purchase order from Boeing.
But it was still, in many ways, an orange growing on an apple tree.
II. The First Bite
As Rossell Techsys grew, so did its dependence on its largest customer.
Boeing consistently accounted for roughly 90% of the company’s revenue.
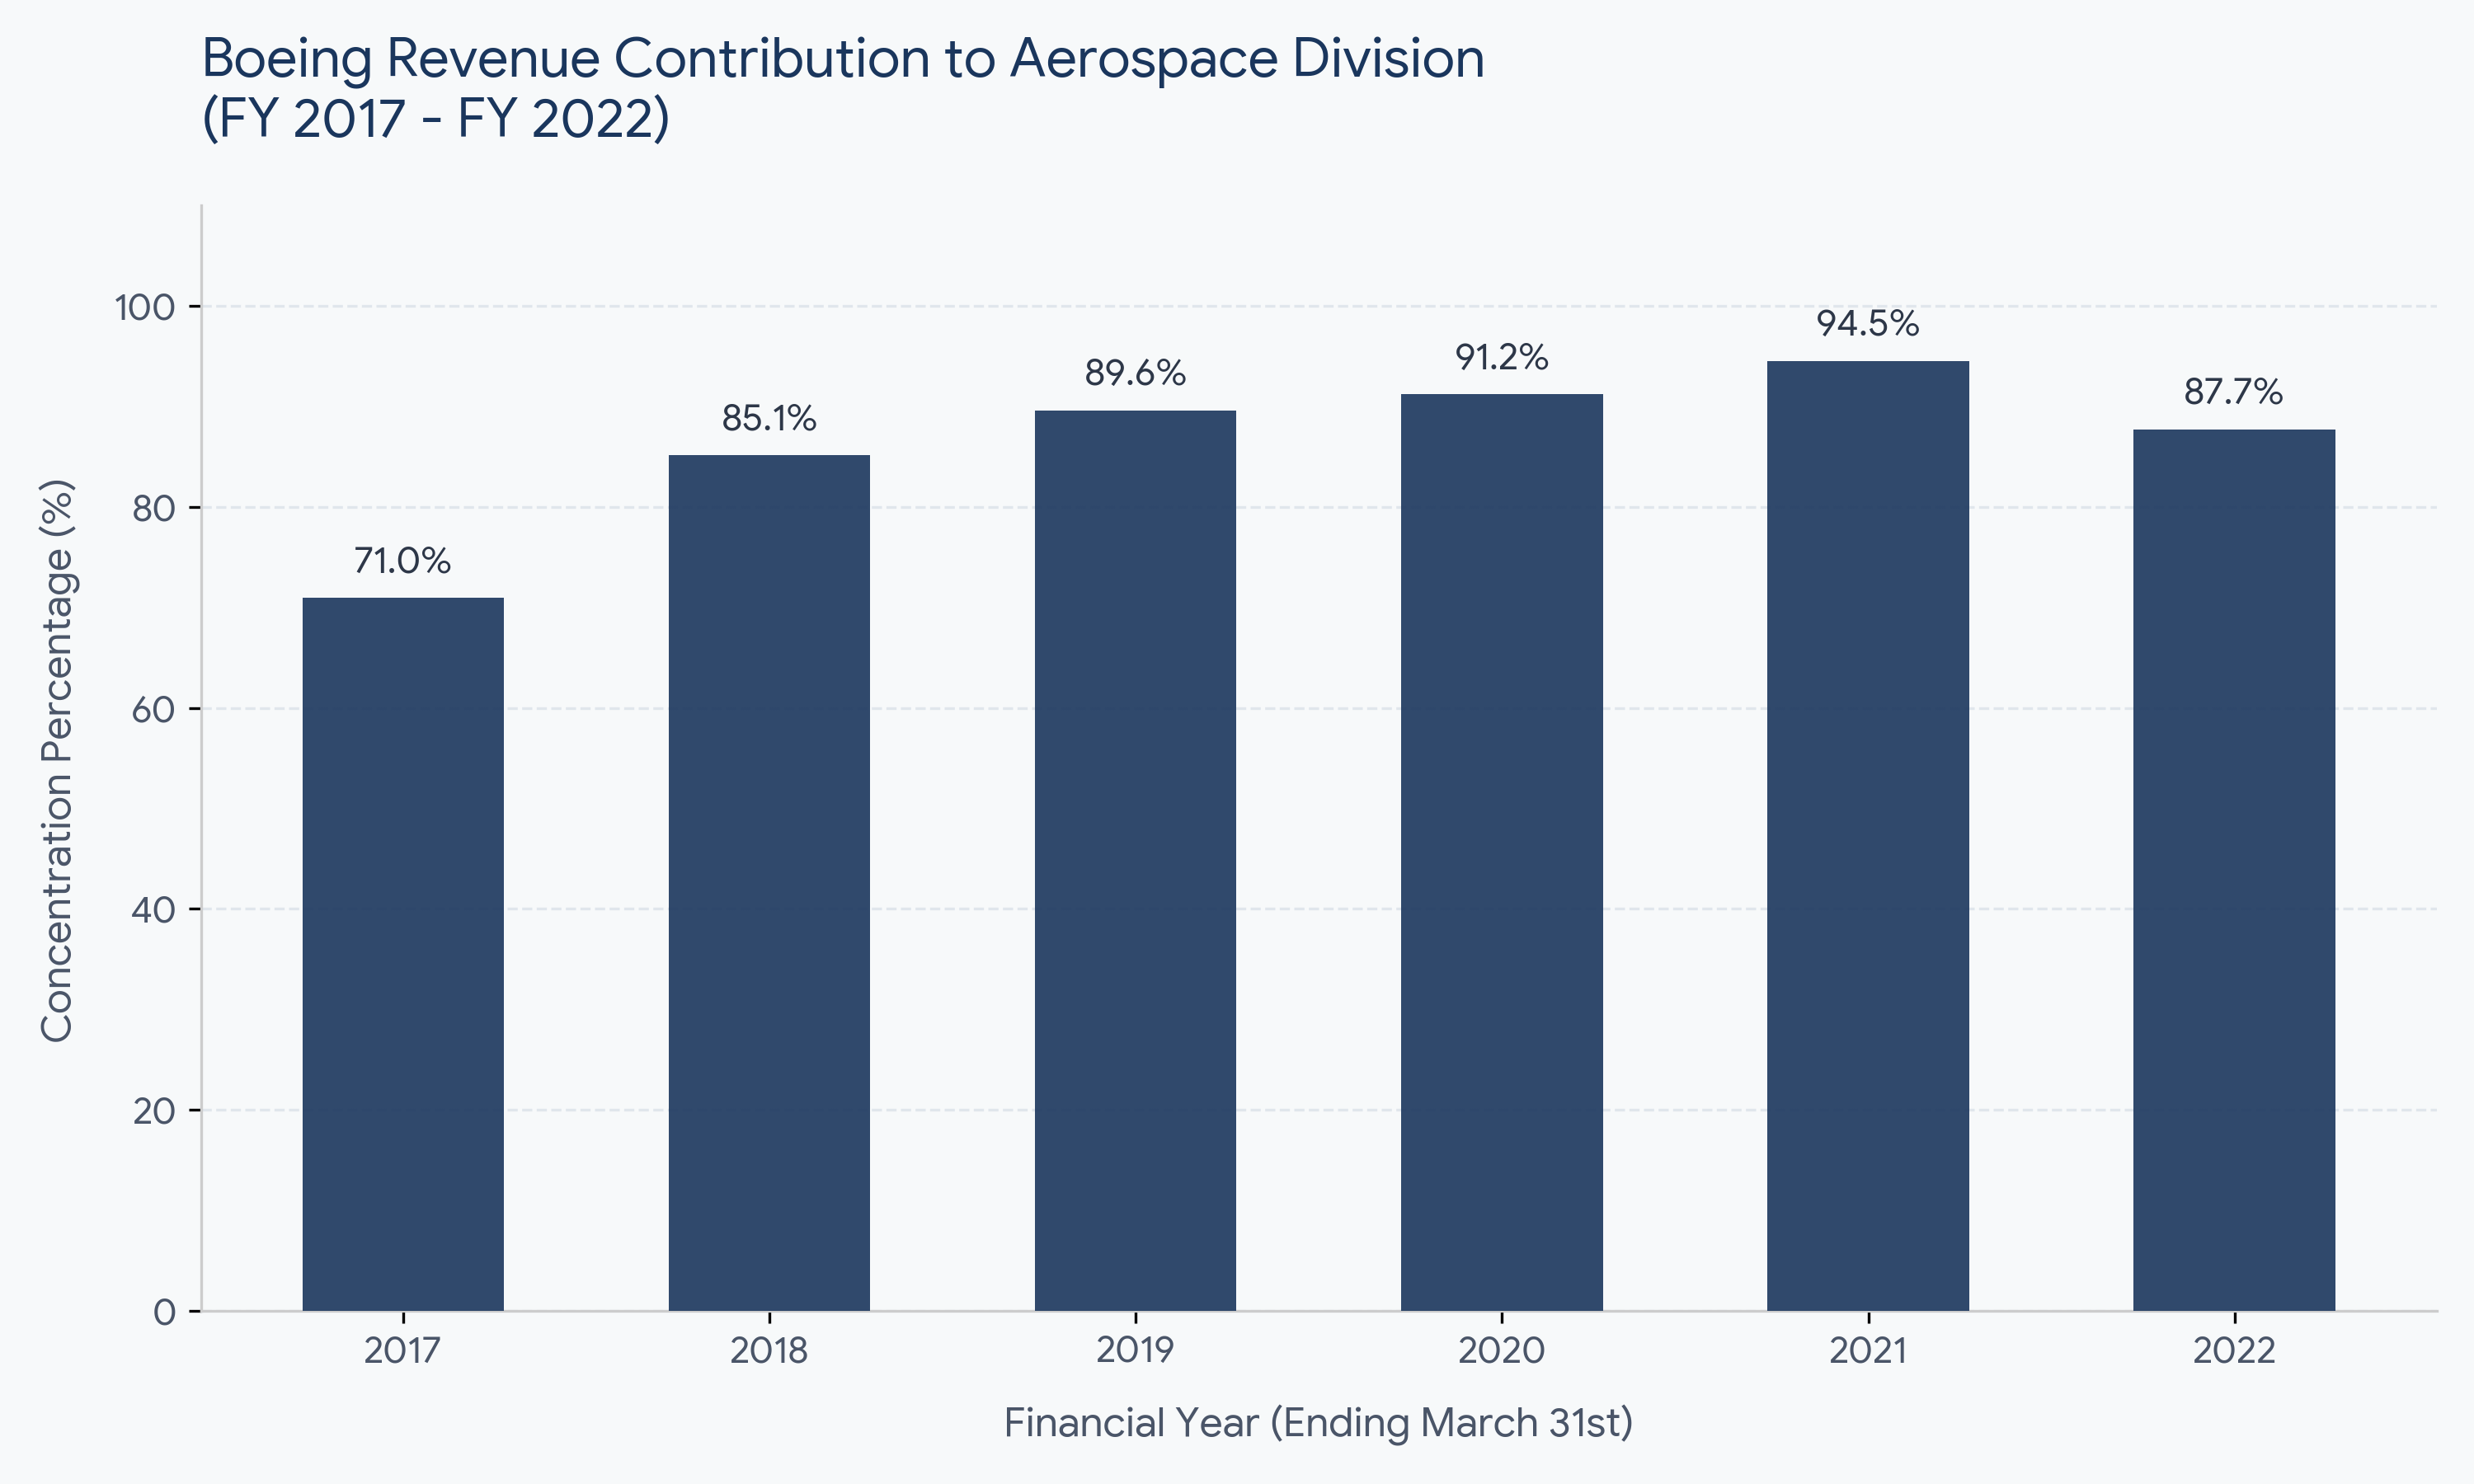
So, at first bite the company left a distasteful conclusion:
This is a Boeing-dependent supplier.
But what if it was never meant to be eaten like an apple?
Perhaps it needed to be peeled.
III. The Same Orange, But Peeled
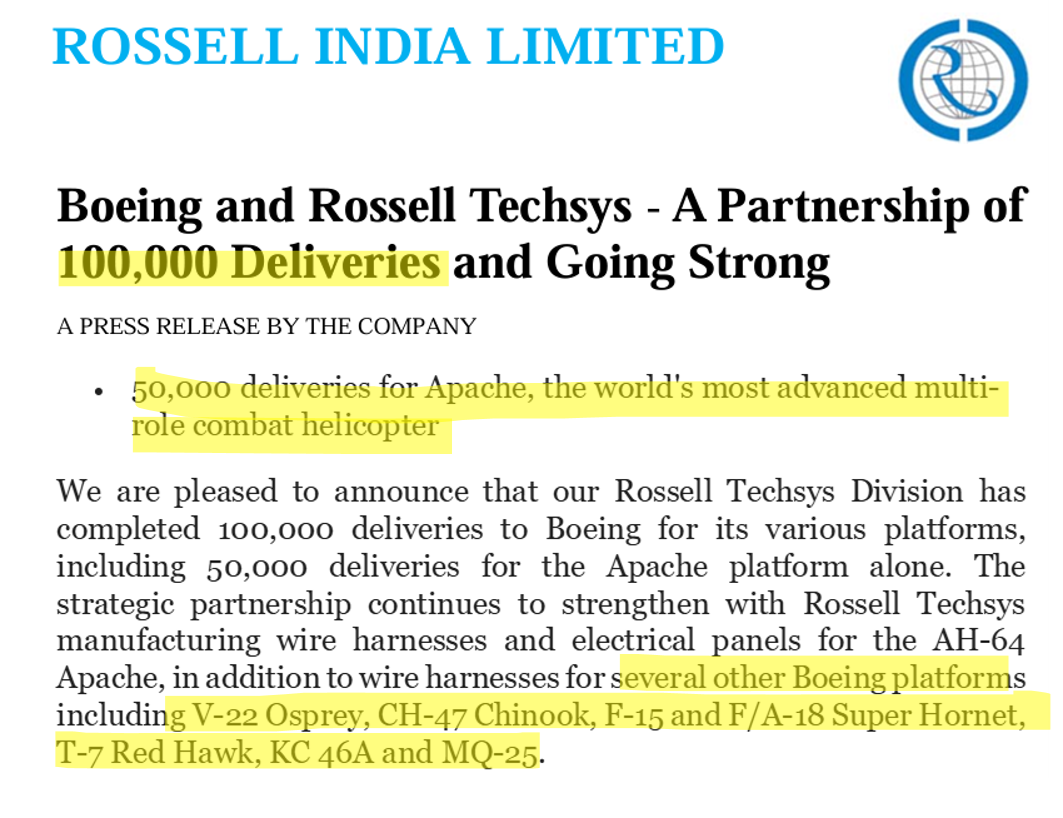
Over the years, Rossell Techsys has embedded itself across a portfolio of Boeing platforms — from fighters and helicopters to maritime patrol aircraft, tankers, trainers and unmanned systems.
Its work spans:
F-15 Eagle: Air superiority fighter
F/A-18 Super Hornet: Carrier-based multirole jet
AH-64 Apache: Premier attack helicopter
CH-47 Chinook: Heavy-lift cargo helicopter
P-8 Poseidon: Maritime patrol aircraft
V-22 Osprey: Joint-venture tiltrotor aircraft
KC-46 Pegasus: Aerial refuelling tanker
MQ-25 Stingray: Unmanned refuelling drone
T-7A Red Hawk: Advanced jet trainer
Many of these platforms continue to see modernisation, while newer ones are moving from development towards production.
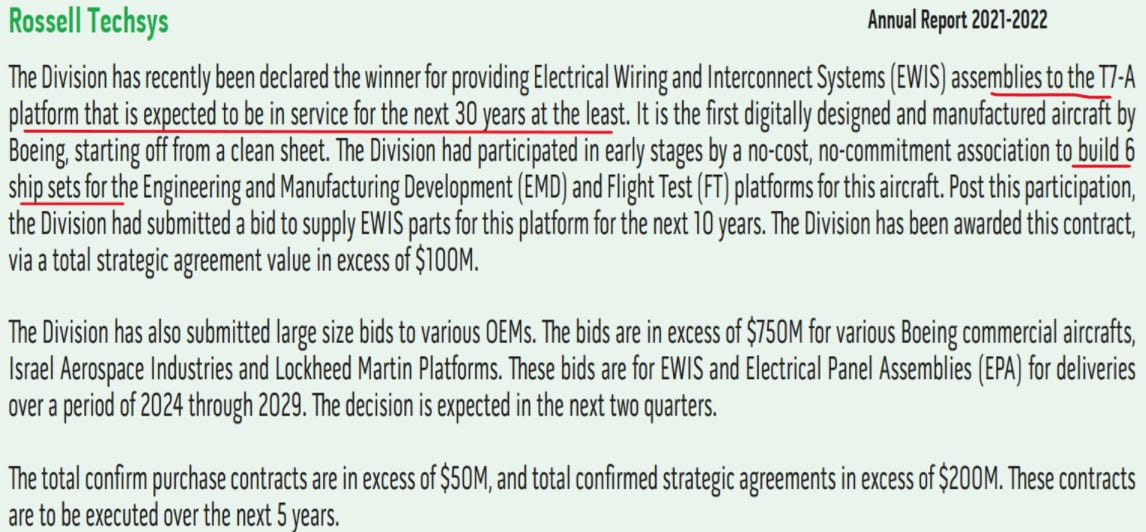
T-7A perhaps illustrates the progression best.
Rossell’s association began with early prototype shipsets for the program.
That relationship subsequently expanded into a 10-year EWIS (Electrical Wiring and Interconnect Systems) contract worth more than US$100 million, followed by an IDIQ (Indefinite Delivery, Indefinite Quantity) contract covering up to 1,200 EPA shipsets through 2033.
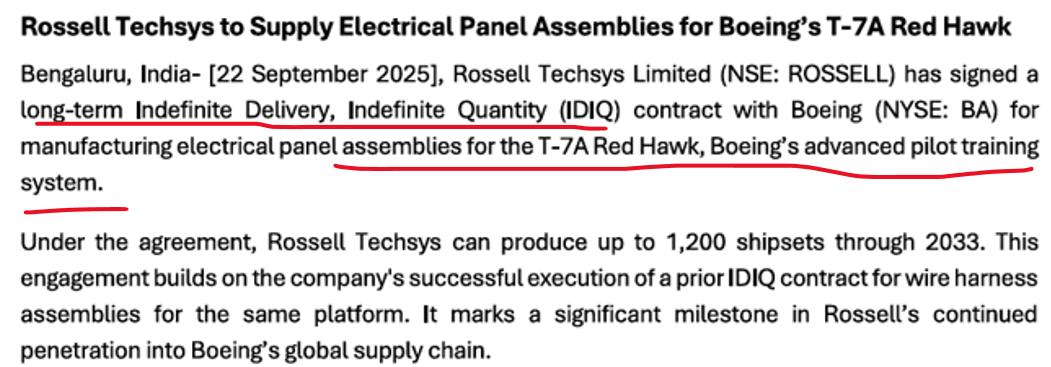
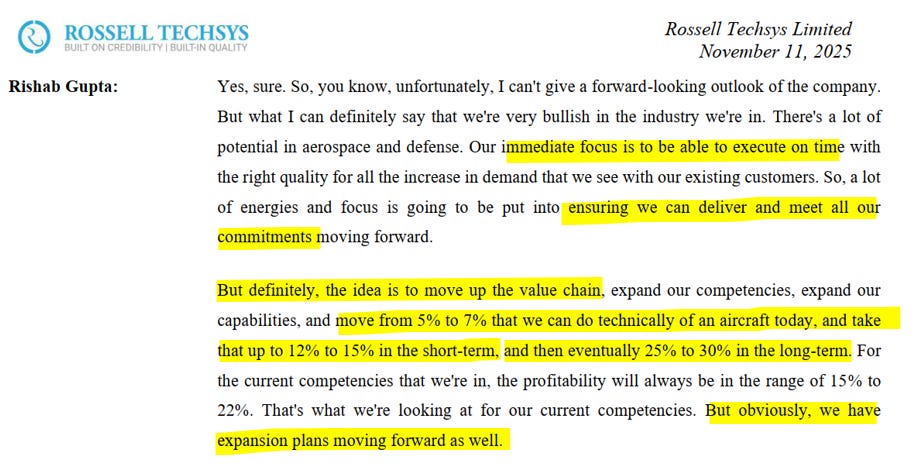
The company then gradually moved from supplying EWIS and harnesses towards Electrical Panel Assemblies, Electronic Sub-System Integration and Automated Test Equipment.
The management has even set an ambition to increase its build content from roughly 2–5% of platform value today to 15–25% integrated electromechanical assemblies
So, with the layer peeled away, it turns out the orange has more inside it.
It has seeds which can grow into an orchard of their own.
IV. The Seeds
If one customer can provide multiple programs and platforms, how large can the opportunity become?
That brings us to the numbers sitting beyond today’s revenue for the company:
₹715–800 crore of confirmed order book.
₹2,800–3,000 crore of strategic agreements over the next 3–5 years.
~₹4,500 crore of active bids.
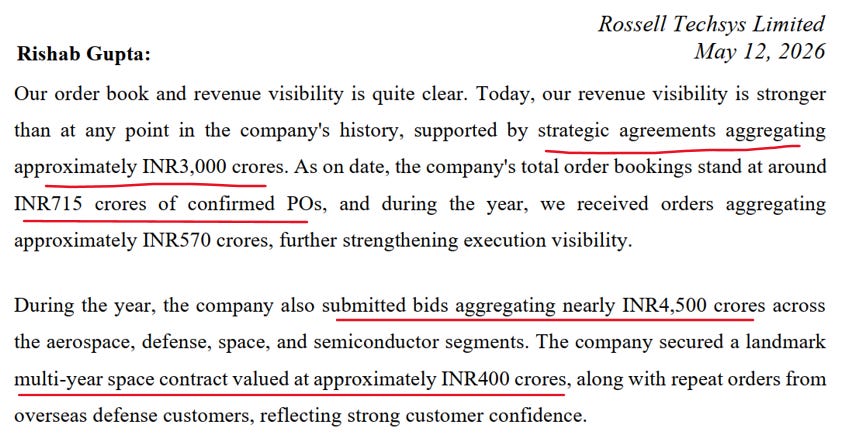
These numbers provide a directional sense of the opportunity being pursued.
It is the expansion of the customer pool that is the strongest growth signal.
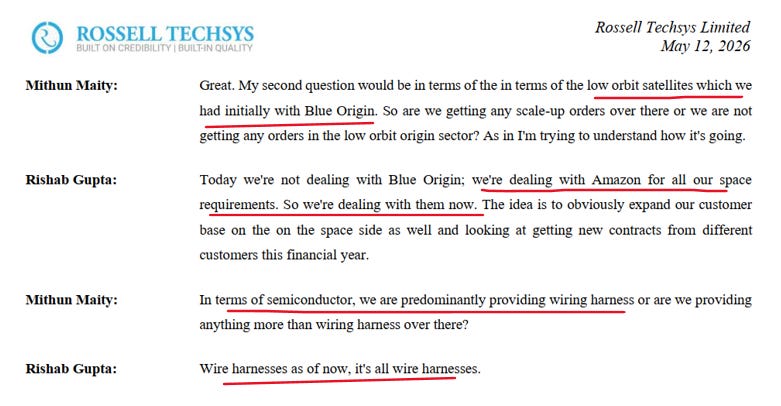
Between 2022 and 2026, Rossell added major global OEMs, including Honeywell, Lockheed Martin, Israel Aerospace Industries (IAI), InterConnect Wiring, SFC Energy, and Telair
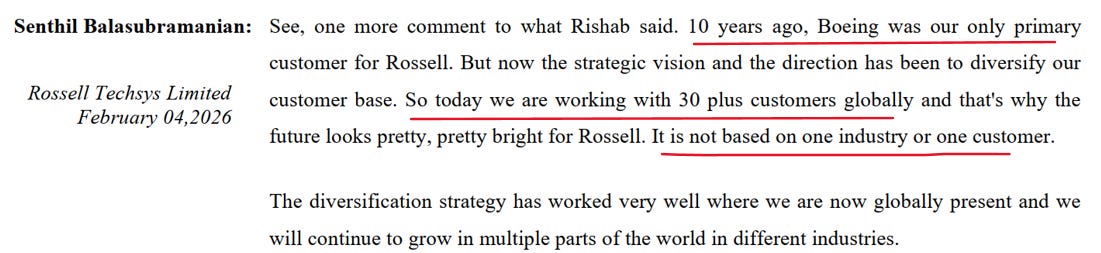
The company made progress not just in diversifying customers but entering new industry segments as well. The semiconductor industry is one such example.
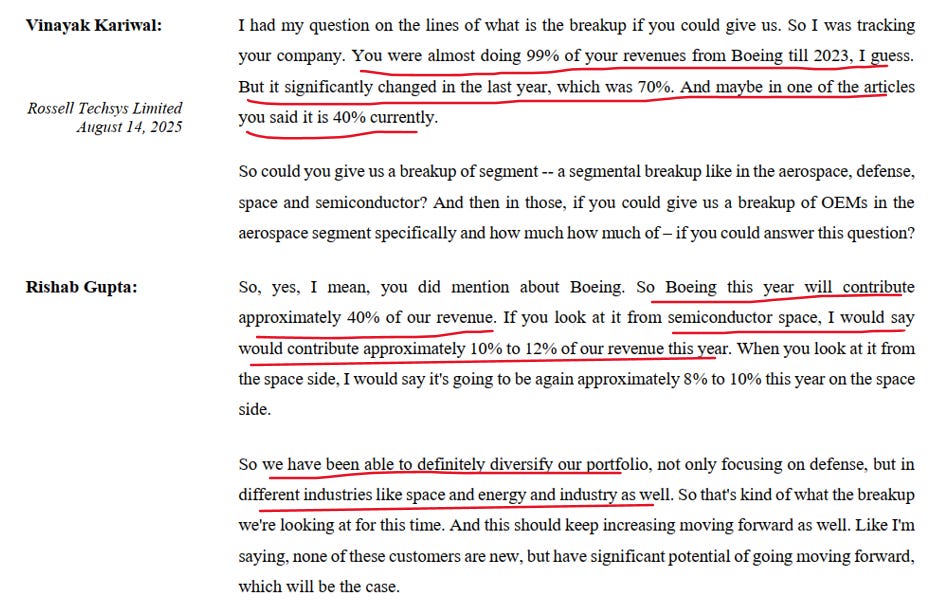
They manufacture specialised wire harnesses and interconnects for machines that fabricate semiconductors (partnering with global equipment makers such as Lam Research - listed as a customer)
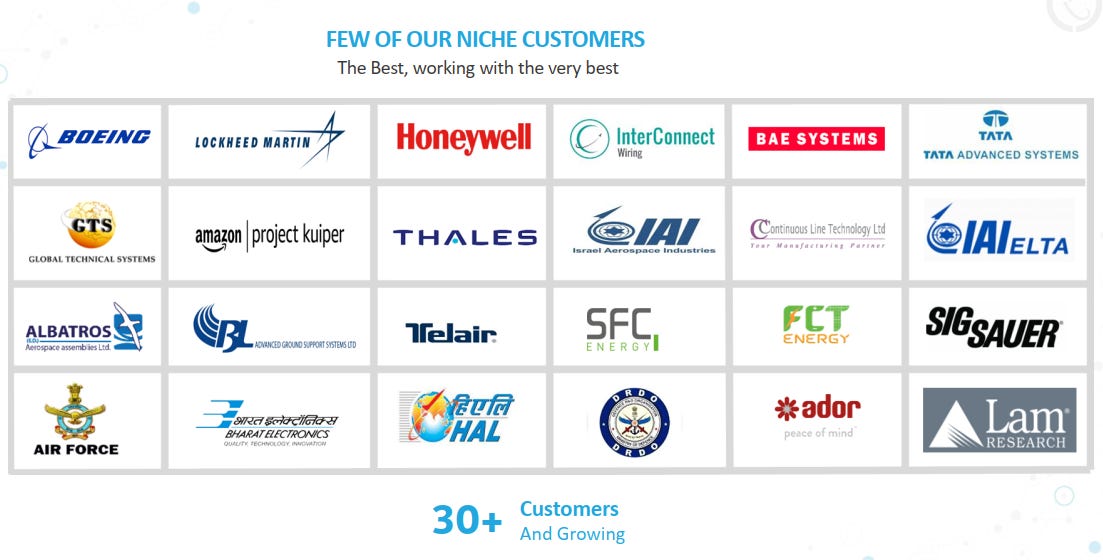
The company also became successful in securing a landmark multi-year space contract valued at ~₹400 Crores (supplying wire harnesses for satellite constellations, including Amazon's Project Kuiper)
Suddenly, the seeds in the orange start to look very valuable.
And this is something the management appears to have recognised as well.
V. The Orchard
Rossell Techsys was once an Aerospace & Defence business sitting inside Rossell India — alongside the tea business.
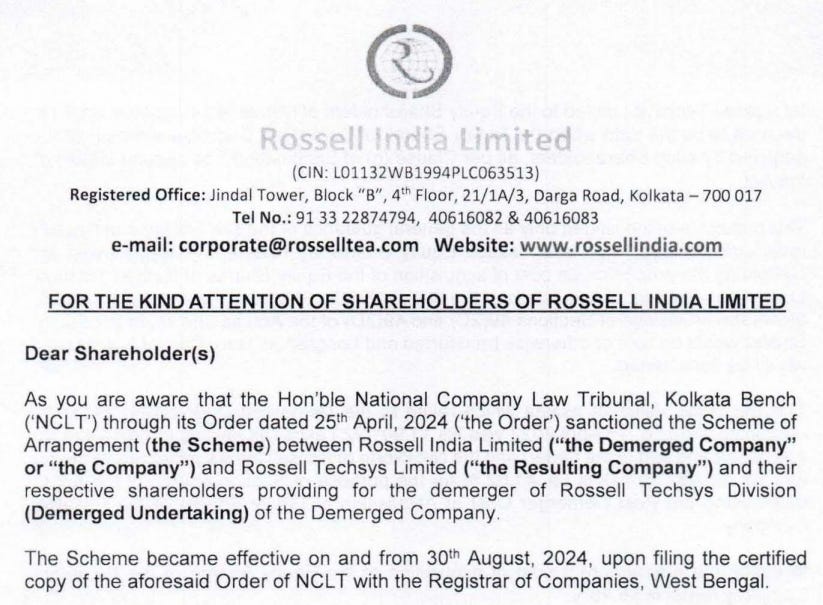
The management demerged the businesses and Rossell Techsys was separated into a pure-play listed entity.
The metaphor is simple:
The orange was no longer growing on the apple tree.
From the original 4,000 sq ft in 2011, Rossell Techsys expanded its manufacturing footprint dramatically — ultimately taking its total facility footprint to around 615,000 sq ft, along with expansion of the employee base - from 25 employees to roughly 1,200 employees by FY26.
Then came the most important development.
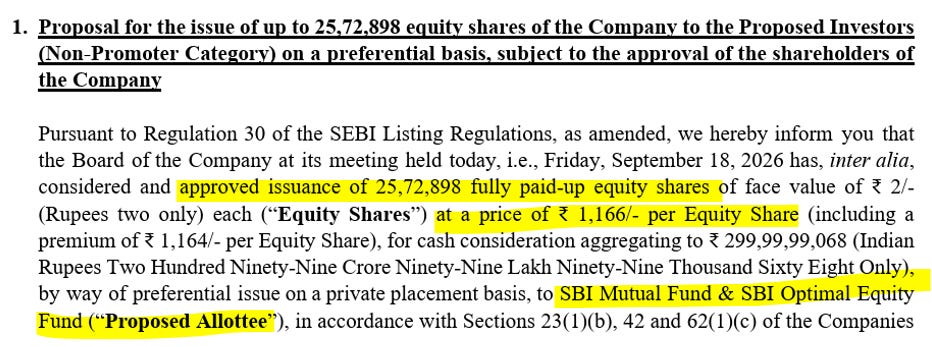
In September 2026, Rossell Techsys announced a ₹300 crore preferential issue to SBI Mutual Fund and SBI Optimal Equity Fund at ₹1,166 per share.
The capital is intended to support:
Capacity expansion
Long-lead working capital
Tooling and automation
Balance-sheet strengthening / debt reduction
VI. Conclusion
To conclude— the story of Rossell Techsys has evolved from that of a Boeing-dependent aerospace supplier into something that looks very different today.
And because success with one customer does not guarantee success with others or capability for a particular industry may not easily flow into others - perhaps it is now left for investors to figure out the orange from the apples, for a change.
Twitter/X Profile: @A_Basumallick
For investing in our PMS, drop us a mail at equity@shreerama.co.in
For our research services, visit https://intelsense.in
Subscribe to our free blog https://intelsense.substack.com
DISCLAIMER:
Intelsense.in is owned by Cupressus Enterprises Pvt Ltd (SEBI Registered Research Analyst) with Registration No. INH000013828
Research Analyst or his associates or his dependent family members may hold a financial interest or actual/ beneficial ownership in the financial products/ securities advised herein.
Investment in the securities market is subject to market risks. Read all the related documents carefully before investing.
Shree Rama Managers LLP is a SEBI-Registered Portfolio Management Services Company (SEBI Reg. Number: INP300007341).
Stocks discussed, if any, are for EDUCATIONAL purposes only and should NOT be construed as investment advice.
Please consult your financial advisor and do your own due diligence before investing.